Pixxel has raised a $100-million Series C, the largest funding round announced by an Indian space-tech company. The round was co-led by Temasek and Seraphim, with participation from 360 ONE Asset, IMM Investment and existing investors. Pixxel said the funding takes its total capital raised to $195 million. Pixxel’s official announcement
The round is a major milestone for India’s Deep Tech ecosystem. It also raises a harder question: are investors valuing Deep Tech companies on future potential in the same way they valued SaaS companies during the 2021 funding boom?
Why Pixxel matters
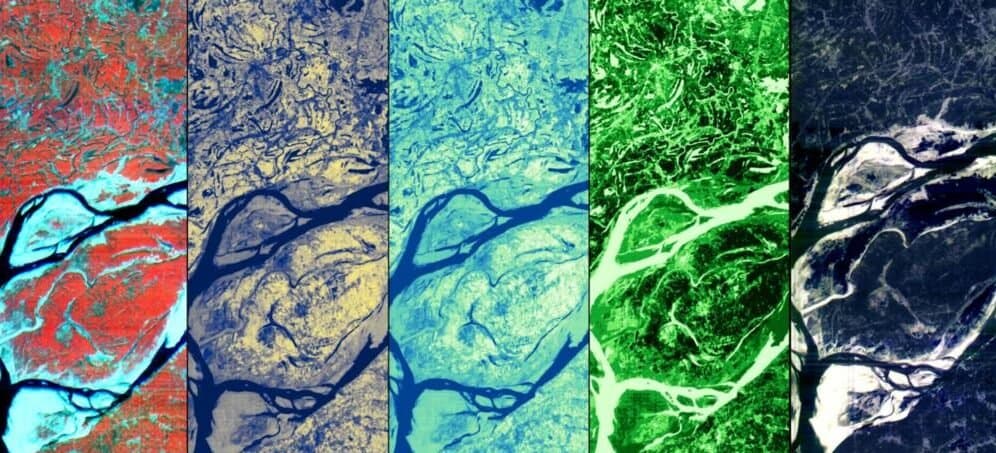
Pixxel develops hyperspectral satellites, Earth-observation data products and satellite systems. Its technology is intended for applications including agriculture, climate monitoring, mining, defence and government. The company is also expanding into spacecraft manufacturing and Earth-intelligence software. Pixxel’s official company profile
Pixxel says it has contracts with organisations including NASA and the US National Reconnaissance Office. It is also leading a consortium working with IN-SPACe to develop a national Earth-observation constellation. Pixxel’s official IN-SPACe announcement
The company’s Series C will fund its Honeybee satellite constellation, Earth-intelligence platform and manufacturing expansion. Pixxel said its first Honeybee satellite is expected to launch in 2027. The funding announcement also says the company plans to expand into synthetic-aperture radar and ultra-high-resolution optical imaging.
According to The Economic Times, an independent valuation report estimated Pixxelspace India’s FY26 revenue at ₹98.15 crore and its net loss at ₹96.62 crore. The report said Pixxel had approximately 35–40 paying customers. It also cited people familiar with the transaction who placed the company’s valuation at approximately $400–450 million. The Economic Times reported these figures.
Pixxel has not officially disclosed its post-money valuation, so the $400–450-million figure should be treated as a reported estimate.
The gap between present revenue and reported valuation is not automatically a problem. Deep Tech companies often raise capital before their products reach commercial scale. They may need years of research, testing, hardware deployment, regulatory approvals, and customer integration.
The important question is what investors are assuming will happen next:
- Will pilot customers sign larger contracts?
- Will contracts become recurring?
- Can the satellite network be built and operated economically?
- Can revenue grow faster than capital expenditure?
India’s Deep Tech funding wave
Pixxel is part of a wider increase in Indian Deep Tech investment.
A Tracxn report cited by Fortune India said India’s private space-tech ecosystem had raised $871 million across 241 funding rounds by July 2026. The ecosystem included 285 companies, although only 72 had secured institutional equity funding.
The sector’s largest recent transactions include:
- Pixxel: $100 million Series C.
- Skyroot Aerospace: $60 million at a reported $1 billion valuation.
- Digantara: approximately $50 million in Series B funding.
- AgniKul Cosmos: approximately $17 million in Series C funding.
- Bellatrix Aerospace: approximately $20 million in Series A funding.
Skyroot’s $60-million round, led by GIC and Sherpalo Ventures, made it India’s first space-tech unicorn at a reported $1.1-billion valuation. Reuters reported on Skyroot’s valuation. These funding figures show investor confidence. They do not, by themselves, establish revenue quality, profitability or repeat customer demand.
Semiconductor funding rises too
The Deep Tech funding story extends beyond space. Indian semiconductor startups raised approximately $92 million across 12 deals in the first five months of 2026, according to The Economic Times.
Examples include:
- Sensesemi Technologies: ₹25 crore seed round led by Piper Serica, according to Entrepreneur India.
- OptoML: $1.8 million funding, according to Electronics For You.
- VerifAIX: $5 million seed round co-led by Endiya Partners and Bluehill VC, according to Indian Startup Times.
Semiconductor startups face a long commercial journey. They need to move from product architecture and prototype development to tape-out, fabrication, testing, customer validation, design wins, and volume production. A successful prototype is therefore not the same as a successful commercial chip.
The SaaS 2021 comparison
The comparison with SaaS comes from the speed and scale of the earlier funding cycle. Investment in Indian SaaS reached approximately $4.5 billion in 2021, a 170% increase from 2020, according to Bain’s India SaaS Report.
The market later became more cautious. Bain’s 2022 report described weaker funding conditions after the record inflows of the previous period. The Zinnov–Chiratae India SaaS Report 2023 documented a correction in pandemic-era valuation multiples and a sharp decline in late-stage funding.
Bessemer Venture Partners reported that the average enterprise-value-to-forward-revenue multiple for its emerging cloud index declined from approximately 25× at the peak to around 6× in the first half of 2023.
The correction did not mean that SaaS stopped being a valuable business. It meant investors became less willing to pay peak-growth prices when growth slowed, public-market technology valuations fell and profitability became more important.
Why Deep Tech is different
Deep Tech should not be treated as SaaS with hardware. Space and semiconductor companies often require:
- Larger research and development budgets.
- Hardware testing and certification.
- Manufacturing capacity.
- Long procurement cycles.
- Government approvals.
- Specialist engineering teams.
- More time before commercial revenue scales.
They may also have stronger barriers to entry and strategic value. A company developing satellite infrastructure, launch systems, or chip design technology may be valuable even before it becomes profitable. For that reason, the absence of near-term profit is not automatically evidence of overvaluation. The more useful question is whether the company has moved beyond technical possibility.
The commercialisation test
Deep Tech investors should track progress through five stages:
| Stage | What it demonstrates | Evidence |
| Technical prototype | The technology works in controlled conditions | Test results and demonstrations |
| Field or orbital validation | The technology works in real conditions | Deployment and operating data |
| Paying customer | A customer is willing to spend money | Purchase order, invoice, or contract |
| Repeat demand | The product is not a one-time project | Renewals or repeat orders |
| Scalable economics | Revenue can grow without equal cost growth | Margins, yields, utilisation and cash flow |
Based on its disclosed satellites, customer contracts and institutional programmes, Pixxel has evidence across several of these early stages.
The company must show that these assets can produce recurring, high-value contracts at a cost that supports a sustainable business.
Where the valuation risk lies
The risk is not that venture capital is funding Deep Tech before profitability. That is normal. The risk is that investors may price a company as though future customers, manufacturing capacity, and recurring revenue are already certain.
A repricing could happen if:
- Government contracts take longer than expected.
- Pilots do not become larger commercial contracts.
- Hardware deployment is delayed.
- Manufacturing costs remain high.
- Launches or satellite operations fail to meet expectations.
- Follow-on funding becomes difficult.
Pixxel’s reported valuation of $400–450 million against estimated FY26 revenue of ₹98.15 crore illustrates why this scrutiny is necessary. The valuation may be justified if the company successfully converts its infrastructure and partnerships into much larger recurring revenue. It may look aggressive if that conversion does not happen.
Conclusion: Deep Tech needs proof beyond the story
Pixxel’s $100-million Series C is a strong signal that global investors believe India can build important space infrastructure. It also shows that Indian Deep Tech has moved from small experimental rounds to large institutional funding.
That does not make the round irrational, nor does it prove that Pixxel is overvalued. The more balanced interpretation is that investors are pricing Pixxel for what it could become: a large Earth-intelligence and space-infrastructure company.
The SaaS correction that followed the 2021 funding boom showed how quickly valuations can reset when growth expectations weaken, and investors place greater weight on profitability and cash generation.
Deep Tech has a longer timeline and different economics, but it faces the same basic test: technology may attract the first round of capital; commercial validation will determine whether the valuation lasts.
Read More: Beyond the digital screen: Why India’s D2C brands are going omnichannel