The Indian urban consumer ecosystem is undergoing a dramatic structural transformation driven by the rapid commoditisation of time. Following the meteoric rise of quick-commerce platforms delivering groceries in minutes, the battleground for instant gratification has shifted into the intimate domain of domestic labor.
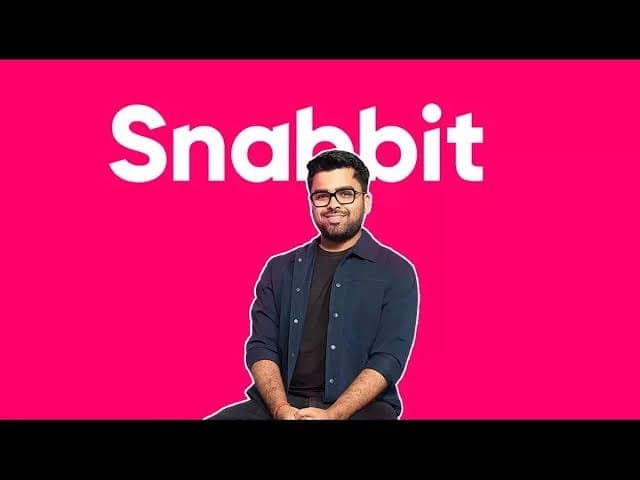
At the very center of this high-stakes market evolution is Snabbit, an instant home-services platform operated by Maestroedge Solutions Private Limited. Newly disclosed financial statements filed with the Registrar of Companies (RoC) and analyzed across major financial outlets including Livemint, Moneycontrol, and The Economic Times reveal the staggering capital intensity required to pioneer an entirely new consumer habit in India’s metro cities.
During its first full financial year of operations in fiscal year 2026 (FY26), Snabbit posted an operational revenue of ₹12.25 crore while enduring a massive net loss of ₹167.75 crore.
This widening financial gap represents a nearly 30-fold expansion from FY25, when Snabbit logged a net loss of ₹5.70 crore against an operating revenue of ₹26.35 lakh. To uninitiated observers, a loss that eclipses top-line revenue by more than thirteen times might resemble an alarming sign of financial distress.
However, Snabbit founder and chief executive officer Aayush Agarwal maintains that these figures reflect a calculated, deliberate strategy to construct a brand-new service category from the ground up rather than a sign of operational inefficiency.
Understanding the economics behind Snabbit requires looking past surface-level profit and loss statements to examine supply chain architecture, micro-market density, unit-level trajectory, and the fierce three-way competitive war currently playing out across India’s major metropolitan hubs.
The Strategic Blueprint: Category Creation vs. Short-Term Margins
Building an on-demand domestic assistance marketplace in India presents structural challenges that traditional tech platforms rarely encounter. Unlike standard e-commerce logistics, where standardized packages are moved from fulfillment centers to doorsteps, domestic work involves human capital, hyper-local trust, standardized quality control, and instant dispatch algorithms.
Snabbit was launched in 2024 to address these exact pain points, providing verified and trained domestic help specializing in chores such as cleaning, dishwashing, and laundry at customer doorsteps within approximately 10 minutes, with prices starting at ₹99 per hour.
Reflecting on the FY26 financial figures in a public statement on LinkedIn and in direct responses to financial media, Snabbit CEO Aayush Agarwal explained that establishing a completely novel consumer habit requires upfront capital deployment that vastly outstrips early platform earnings.
Agarwal emphasized that Snabbit made a deliberate choice to invest aggressively ahead of scale to construct a lasting category rather than focusing on premature profitability. In his view, building the foundational layer of technology, workforce onboarding, background verification, and neighborhood presence necessitates heavy early spending.
This capital-intensive philosophy is backed by Agarwal’s deep operational lineage in India’s quick-services domain. An alumnus of the Institute of Management Technology (IMT), Ghaziabad, where he earned a Post Graduate Diploma in Management (PGDM) in Finance, Agarwal initially worked as a finance manager at White Owl before joining quick-commerce pioneer Zepto in 2022.
At Zepto, he rose from senior finance manager to Vice President and Chief of Staff, gaining firsthand experience in scaling hyper-local delivery networks before founding Snabbit in 2024. His background at Zepto heavily influenced the aggressive, land-grab playbook that defined Snabbit throughout its first full year of operations.
Deconstructing the FY26 Income Statement and Cost Architecture
A detailed breakdown of Snabbit’s FY26 balance sheet filings, as reported by financial news platforms and data tracker TheKredible, provides a clear view into where investor capital was deployed. Total expenses for Snabbit skyrocketed to ₹194.76 crore in FY26, compared to just ₹6.81 crore during the partial operational period of FY25.
Against these expenses, Snabbit generated a total income of ₹27.01 crore, which was composed of ₹12.25 crore in revenue from core operations and ₹14.77 crore in other income derived primarily from interest earned on bank deposits following successful equity fundraises.
The operational revenue of ₹12.25 crore reported by Snabbit is recorded net of platform-funded customer promotions and bill discounts designed to lower trial barriers for urban households. A closer look at the top-line revenue reveals two distinct streams: core platform service fees contributed ₹10.82 crore, while the direct sale of branded uniforms and equipment to service professionals generated ₹1.42 crore.
On the expenditure side, Snabbit spent heavily across four major operational verticals:
- Professional and Service Costs: The single largest expense item for Snabbit was direct payouts to its service professionals (designated internally as “Experts”), which totaled ₹63.07 crore. This reflects the high cost of retaining reliable supply and ensuring availability for instant 10-minute dispatch.
- Marketing and Brand Acquisition: Snabbit allocated ₹48.69 crore toward marketing campaigns, digital user acquisition, and promotional subsidies to drive brand awareness across new territories.
- Employee Benefit Expenses: Internal corporate payroll, engineering talent, operational managers, and administrative overhead accounted for ₹46.02 crore.
- Service Fulfilment Expenses: Direct logistics dispatch, customer support mechanisms, and ground operations required ₹23.83 crore.
- Other Overhead and Depreciation: Additional administrative expenses and operational overhead totaled ₹84.66 crore, alongside ₹1.02 crore in depreciation costs.
Because Snabbit recorded no current or deferred tax liabilities for the fiscal year, its loss before tax stood at exactly ₹167.75 crore.
The Economics of Density: Unit Loss Contraction and 75x Scale

While a net loss of ₹167.75 crore highlights intense cash burn, Snabbit leadership points to rapid improvements in unit economics as evidence of long-term viability. In early startup growth phases, aggregate annual profit and loss statements often obscure the operational gains achieved month-over-month at the individual transaction level.
According to metrics shared by Agarwal, Snabbit began FY26 losing approximately ₹1,500 on every completed job. By the end of the fiscal year, as order volumes concentrated and geographic route optimization took hold, Snabbit reduced its unit loss to below ₹200 per job. Management projects that this trend will continue as individual micro-markets mature into positive contribution margins.
This contraction in unit-level burn was accompanied by massive operational scaling across urban centers:
- Daily Transaction Throughput: Snabbit entered FY26 completing roughly 500 jobs per day across 8 micro-markets. By the close of the 12-month period, Snabbit was executing a daily run rate of 35,000 jobs across more than 100 micro-markets, marking a 70x to 75x surge in operational scale.
- Customer Base Expansion: Over the course of its first full financial year, Snabbit acquired nearly 1 million unique customers.
- Supply Chain Onboarding: To support high demand, Snabbit successfully onboarded, verified, and equipped over 20,000 Experts.
The underlying thesis for Snabbit hinges on neighborhood density. In a service model promising worker arrival within 10 minutes, micro-market order volume dictates profitability.
Higher order density in a specific neighborhood minimizes transit distance between assignments for Experts. This enables service workers to complete more bookings per shift, driving down fulfillment costs and unlocking operating leverage for Snabbit.
Capital War Chest and Balance Sheet Fortress
Navigating prolonged periods of market building requires immense institutional backing. To date, Snabbit has secured over $112 million (exceeding ₹1,000 crore) in venture capital across five distinct equity funding rounds.
A major financial milestone for Snabbit occurred in April 2026, when the company closed a $56 million Series D funding round. The Series D investment was co-led by Susquehanna Venture Capital (SIG), Mirae Asset Venture Investments, and existing backer Unicorn Growth Fund. The round also saw participation from existing institutional investors Nexus Venture Partners and Lightspeed, along with new investor FJ Labs. This funding round pushed Snabbit’s post-money valuation into the $350 million to $400 million range.
According to official disclosures, Snabbit raised a total of ₹427.8 crore during FY26 alone. The company ended the fiscal year on March 31, 2026, holding approximately ₹319 crore in liquid cash reserves and short-term bank investments.
Furthermore, Snabbit maintains a pristine debt profile with zero outstanding borrowings and a healthy net worth of ₹312.4 crore. This cash reserve grants Snabbit substantial financial runway to fund ongoing operations, absorb short-term losses, and continue expanding its footprint without immediate capital strain.
The Three-Way Competitive Battle: Snabbit, Urban Company, and Pronto
Snabbit does not operate in a vacuum. The quick home-services sector in India has rapidly consolidated into a fierce three-way battle featuring Snabbit, market incumbent Urban Company (through its dedicated Insta Help vertical), and General Catalyst-backed startup Pronto.
All three players are spending aggressively to habituate urban households to instant home help while competing for a finite pool of skilled service professionals. Industry estimates reported by Moneycontrol indicate that Snabbit, Urban Company (Insta Help), and Pronto collectively burned around ₹150 crore in the single month of June 2026 alone as introductory promotional discounts, customer acquisition incentives, and worker retention payouts reached peak intensity.
Order volume data from mid-2026 illustrates how closely matched the top contenders have become:
- Urban Company (Insta Help): Processed approximately 1.9 million completed orders in July 2026, maintaining a slim lead.
- Snabbit: Completed approximately 1.85 million orders in July 2026, running practically neck-and-neck with the established market leader.
- Pronto: Logged over 1.25 million completed orders during the same monthly period.
To safeguard its market share against Snabbit’s aggressive growth, Urban Company has signaled that losses within its Insta Help division will remain elevated. In October 2026, Urban Company’s board convened to evaluate raising $200 million through a Qualified Institutional Placement (QIP) to bolster its balance sheet for the ongoing market-share battle.
Simultaneously, rival challenger Pronto expanded its financing by securing a $20 million extension to its Series B round in May 2026, raising its total Series B capital to $45 million.
Key Analytical Takeaways and Strategic Outlook for Snabbit
As Snabbit transitions into its second full year of operational maturity, the fundamental question facing investors and industry analysts is whether its high-burn category creation strategy can successfully yield long-term profitability. The transition from land-grab expansion to sustainable unit economics will be the defining theme for Snabbit over the next fiscal cycle.
The core analytical conclusions regarding Snabbit’s trajectory include the following key pointers:
- Pioneering Category Creation at Scale: Snabbit demonstrated that consumer demand for instant 10-minute domestic help is real and rapidly expanding, as evidenced by scaling from 500 to 35,000 daily jobs and completing 1.85 million monthly orders in July 2026.
- Clear Path to Unit Economic Improvement: By contracting per-job unit losses from ₹1,500 down to under ₹200 across FY26, Snabbit has shown that micro-market density directly drives operational efficiency and lowers fulfillment expenses.
- Robust Capital Runway: Ending FY26 with ₹319 crore in liquid cash, zero debt obligations, and over $112 million in cumulative venture funding gives Snabbit the financial stability needed to survive high industry burn rates.
- High Supply-Side Reinvestment: Spending ₹63.07 crore on expert service payouts and ₹1.42 crore on uniforms underscores that worker retention and standardization remain Snabbit’s primary operational moat.
- Intense Competitive Pressure: With rivals like Urban Company evaluating a $200 million QIP raise and Pronto expanding its capital reserves, Snabbit must maintain high growth rates while systematically trimming customer acquisition subsidies.
Ultimately, the FY26 financial statements of Snabbit illustrate the classic tech-enabled trade-off between short-term losses and long-term market leadership. If Snabbit can continue optimizing its supply density and shift customers from subsidized trial bookings to organic, full-price repeat usage, the massive ₹168 crore investment made in FY26 may well be remembered as the foundation of a dominant consumer service platform.
Also Read:The Profitability Paradox: Can India’s Tech Unicorns Grow Up Without Burning Out?