Marico is buying access to a faster-growing consumer category while using staged payments to retain founder involvement. The deal shows how established FMCG companies are acquiring digital-first brands to expand their portfolios, rather than relying entirely on internal product development.
What Marico bought
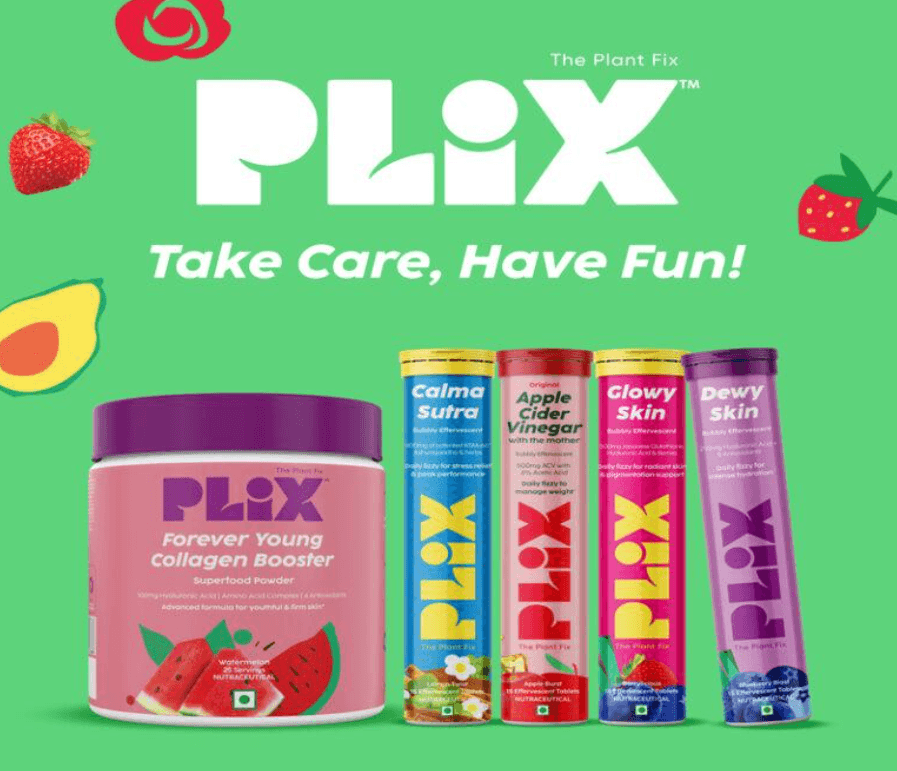
On 5 October, Marico acquired an additional 24.09% stake in Satiya Nutraceuticals, the parent company of Plix, for ₹1,012.03 crore. That lifted its holding from 60% to 84.09% on a fully diluted basis. Marico’s stock-exchange filing confirmed the transaction.
Marico’s cumulative consideration for its current 84.09% stake is ₹1,392.07 crore. It will acquire the remaining 14.09% in July 2027 for a base consideration of up to ₹592 crore, plus milestone-linked payments. The Economic Times reported the deal structure.
Plix reported consolidated turnover of ₹864.31 crore in FY26, up from ₹432.84 crore in FY25 and ₹155.32 crore in FY24. Indian Startup News reported the revenue trajectory. At an implied equity value of about ₹4,200 crore, Marico is paying roughly 4.9 times Plix’s FY26 revenue.
The deal maths
In July 2023, Marico announced its initial investment in Plix, agreeing to acquire a majority stake for ₹369.01 crore. The transaction included fresh capital, so the implied valuation should not be treated as directly comparable with a later secondary share purchase.Marico’s July 2023 exchange filing set out the structure.
Three years later, the latest tranche implies an equity value of about ₹4,200 crore: ₹1,012.03 crore for 24.09% works out to roughly ₹4,200 crore on a fully diluted basis.
That means Plix’s implied valuation has risen roughly 6.5 times since 2023, while its revenue has grown about eight times from ₹106.43 crore in FY23 to ₹864.31 crore in FY26. Indian Startup News reported the revenue growth.
| Year | Plix revenue | Implied equity value |
| FY23 | ₹106.43 crore | — |
| July 2023 deal | — | About ₹636 crore |
| FY26 | ₹864.31 crore | About ₹4,200 crore |
Marico is paying roughly 4.9 times FY26 revenue today, compared with roughly 6 times FY23 revenue implied by the 2023 transaction. The deal looks expensive in absolute terms, but cheaper relative to revenue.
Why FMCG companies buy D2C brands

Large FMCG companies have distribution, manufacturing, regulatory expertise and balance-sheet strength. What they often lack is speed in digital-first categories.
The strategic logic is straightforward. Digital-first brands are often better at identifying new consumer needs, testing products online and building early demand. But as they scale, customer-acquisition costs can rise and profitability becomes harder to sustain. Incumbents bring distribution, supply chains and lower-cost capital.
Marico can offer Plix wider offline distribution, manufacturing and supply-chain support, regulatory expertise and access to a larger consumer base. In return, Marico gets exposure to categories where its legacy brands may not grow fast enough.
Why staged acquisitions work
Marico did not buy Plix outright in 2023. It bought control in stages and retained founders through the scale-up phase.
The structure reduces upfront risk: Marico paid ₹369 crore in 2023, not ₹4,200 crore. It also keeps founders working, because the remaining 14.09% is due only in July 2027, with milestone-linked payments.
The milestone-linked final payment gives Marico some protection, but the company is still committed to acquiring the remaining stake under the agreed structure.
This is becoming a standard playbook for Indian FMCG acquisitions.
ITC’s Yoga Bar playbook
ITC first announced its Yoga Bar investment in January 2023. It acquired 39.42% of Sproutlife Foods for ₹175 crore in May 2023, then increased its holding to about 47.5% with a further ₹80-crore investment. In September 2026, it bought the remaining 52.5% for about ₹645 crore, taking ownership to 100%. Indian Startup News reported the staged acquisition; Moneycontrol reported the full buyout.
ITC’s approach is similar to Marico’s: acquire a minority or controlling stake first, test the brand’s growth, then complete the buyout once the business has scaled.
HUL’s Minimalist deal
HUL used a comparable structure with Minimalist.
In January 2025, HUL agreed to acquire 90.5% of Uprising Science, Minimalist’s parent, at a pre-money enterprise value of ₹2,955 crore. The transaction included a ₹2,670-crore secondary buyout and a ₹45-crore primary infusion. HUL completed the acquisition in April 2025 for ₹2,706.44 crore. HUL’s press release described the structure.
HUL also agreed to acquire the remaining 9.5% about two years after completion, while the founders continued to manage the business. The Economic Times reported the founder-retention structure.
ITC’s wider D2C strategy
ITC has applied the same approach across categories. It agreed to acquire Prasuma through a staged transaction, initially buying 43.8% of Ample Foods for about ₹131 crore. It also plans to acquire the remaining 73.5% of Mother Sparsh Baby Care, in which it already held 26.5%, over two to three years. Indian Startup News reported ITC’s D2C strategy.
ITC said its digital-first and organic portfolio, including Yoga Bar, 24 Mantra, Prasuma, Meatigo and Mother Sparsh, had an annualised revenue run rate of more than ₹1,350 crore. Indian Startup News reported the portfolio scale.
What Marico gets from Plix
Plix operates in plant-based nutrition and personal care. Marico said the acquisition expands its addressable market in value-added foods and nutrition while strengthening its presence in personal care and wellness. Indian Startup News reported Marico’s rationale.
Marico’s core portfolio includes edible oils, hair care, male grooming and foods. Plix gives it exposure to younger, health-conscious consumers who may not buy its traditional brands.
Marico separately said it expects double-digit revenue growth and mid-twenties operating profit growth in the September quarter. The Economic Times reported the guidance.
The risk in the model
Marico is paying a high price for growth. Plix’s ₹4,200-crore implied valuation is nearly 4.9 times FY26 revenue. That is reasonable only if revenue keeps growing and margins improve.
Marico said in May 2025 that Plix delivered a low single-digit EBITDA margin in FY25, showing that scale has not yet translated into strong profitability.
The risks include rising customer-acquisition costs, slower D2C growth, competitive pressure from larger FMCG brands, margin pressure from offline expansion, founder attrition and integration challenges. The milestone-linked final payment protects Marico somewhat, but the ultimate cost could rise if Plix performs well.
Conclusion
Marico’s increased stake in Plix is part of a wider FMCG playbook: buy digital-first brands in stages, retain founders, use incumbent distribution to scale them, and complete the buyout only after growth is proven.
Plix’s revenue has grown from ₹106.43 crore in FY23 to ₹864.31 crore in FY26. Its implied valuation has risen from about ₹636 crore in 2023 to about ₹4,200 crore today. Indian Startup News reported the revenue growth; Marico’s exchange filing set out the deal terms.
Marico is not buying a brand. It is buying a growth engine—and paying in stages to keep its founders running that engine.
Read More: Battery Smart Wants to Go Public. Is Swapping a Business or a Battery Rental Scheme?